
Most banks that piloted AI agents in 2024 hit the same wall: the demo worked, but production stalled. Integration with legacy core banking systems took months instead of weeks, compliance teams raised questions no one had anticipated, and the internal AI engineers who were supposed to own the rollout simply did not exist yet. Globally, 79% of enterprises have adopted AI agents in some form, yet only 11% run them in production – a gap analysts now call the production-readiness problem, and it is particularly acute in banking where regulatory requirements add another layer of complexity to every deployment decision. Follow this article to understand the highest-ROI use cases of AI agent for banking, the deployment architecture that actually survives regulatory scrutiny, and the evaluation criteria that will help your institution move from pilot to production in weeks, not quarters.
Key Takeaways
|
What Are AI Agents for Banking?
AI agents for banking are autonomous software systems that perceive context, make decisions, and execute multi-step financial workflows without continuous human input. They connect directly to live systems – core banking platforms, CRM databases, AML watchlists – and act on data rather than simply responding to queries about it.
This distinction separates AI agents from the chatbots most banks deployed between 2019 and 2023. A chatbot responds to a scripted menu. An AI agent receives an unstructured loan application, pulls the applicant’s credit file, cross-checks it against eligibility rules, routes edge cases to a human reviewer, and logs the full decision trail for audit – all autonomously, in sequence, without a human triggering each step.
|
Criteria |
Traditional Chatbot |
AI Agent |
|
Decision type |
Scripted responses |
Autonomous, context-aware decisions |
|
Workflow scope |
Single-step |
Multi-step, end-to-end |
|
System integration |
Surface-level API query |
Deep integration (read + write + trigger) |
|
Learning capability |
Static unless redeployed |
Continuous via RAG and memory layers |
|
Compliance logging |
Minimal |
Full audit trail, role-based access |
|
Best fit |
FAQ, simple routing |
KYC, fraud detection, loan processing |
For banks operating in regulated environments, the audit trail and deep integration capability are not optional features. They are the baseline requirement for any AI deployment that touches customer data or credit decisions. Getting this wrong at the architecture stage means a full rebuild later – which is exactly where most stalled pilots end up.
Top AI Agent Use Cases in Banking By ROI (2026)
In 2025 alone, 50 of the world’s largest banks announced more than 160 AI agent use cases, according to McKinsey – a clear signal that the market has moved past experimentation. We track enterprise AI agent use cases across BFSI workflows continuously, and the five below consistently deliver the highest measurable ROI across banking deployments.
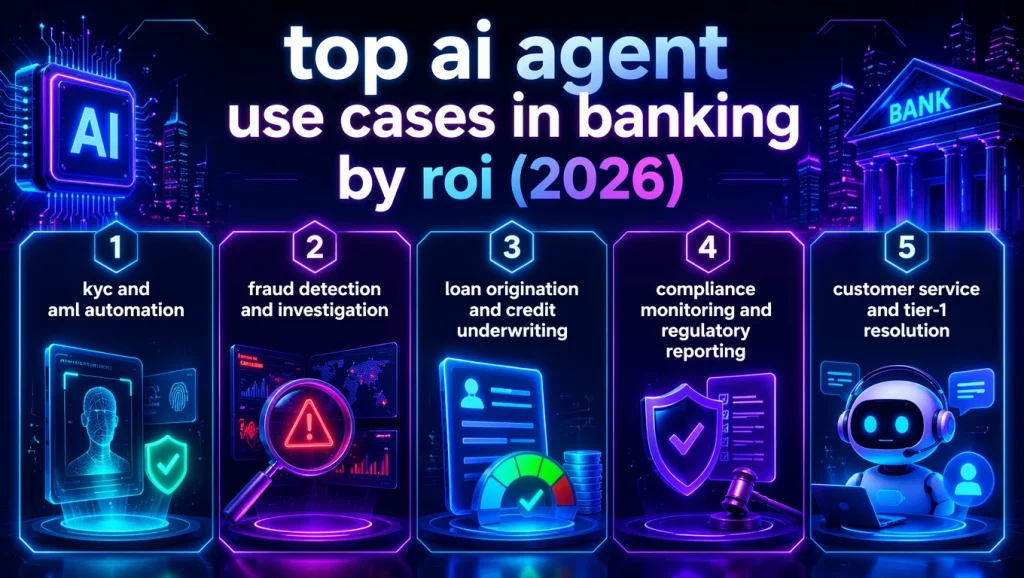
1. KYC and AML Automation
KYC processing traditionally required five days of manual document review, cross-referencing, and compliance sign-off. AI agents compress this significantly by automating document OCR, identity verification, and AML watchlist screening in a continuous workflow. A large Dutch financial institution achieved a 90% reduction in onboarding time and 30% cut in staff workload by applying agentic AI to its KYC and compliance processes – one of several documented outcomes compiled from Deloitte’s 2026 financial services research. The agent handles the standard path autonomously, while human compliance officers review flagged edge cases – meaning their time goes to genuine risk decisions, not routine data entry.
2. Fraud Detection and Investigation
Fraud detection is where AI agents demonstrate their most measurable advantage over rule-based systems. By analyzing transaction patterns across multiple data sources simultaneously and updating risk models continuously, agents catch anomalies that static thresholds miss. Mastercard’s AI-powered fraud detection improved identification by an average of 20%, and up to 300% in specific transaction categories. For regional banks without Mastercard’s infrastructure budget, a well-configured AI agent on a production-grade platform delivers comparable pattern-recognition capability without the enterprise licensing cost.
3. Loan Origination and Credit Underwriting
AI-powered loan processing has demonstrated a 90% increase in accuracy and a 70% reduction in processing times in documented deployments, with approval cycles compressing from days to under 60 seconds for standard applications. AI agents handle data aggregation, scoring model application, and initial eligibility determination. Credit officers retain final authority on complex or high-value cases – a human-in-the-loop design that satisfies both the efficiency objective and regulatory expectations around algorithmic decision-making.
4. Compliance Monitoring and Regulatory Reporting
McKinsey projects a 15-20% net cost reduction across the banking industry from AI deployment in compliance workflows alone. Compliance agents monitor transaction streams continuously, generate regulatory reports automatically, and maintain auditable decision logs – replacing workflows that previously consumed 50+ hours per week of manual analyst time in mid-sized institutions.
5. Customer Service and Tier-1 Resolution
An American financial institution’s employee-facing AI agent reduced calls to the human IT desk by more than 50%, per Deloitte’s 2026 research. For customer-facing deployments, AI agents resolve account inquiries, transaction disputes, and onboarding requests without human intervention for standard cases, escalating only when a request falls outside defined parameters.
How to Evaluate an AI Agent Platform for Banking
Most platform evaluations stall because they focus on the wrong things. Banks compare demo quality, LLM brand names, and feature lists – and miss the questions that actually predict production success. The following framework reflects what separates platforms that reach production from those that remain in pilot indefinitely.
|
Criteria |
What to Look For |
Red Flags |
|
Deployment model |
On-premise + cloud hybrid, air-gap support |
Cloud-only, no data residency option |
|
LLM flexibility |
Model-agnostic: GPT, Claude, Llama, Gemini |
Locked to one LLM provider |
|
Time to first agent |
Under 4 weeks for standard use cases |
“6-18 month” implementation timelines |
|
Compliance coverage |
GDPR, PCI-DSS, SOC 2, HIPAA built-in |
Compliance offered as a paid add-on |
|
Pricing transparency |
Per-agent or subscription, published rates |
Hidden enterprise pricing requiring an NDA |
|
Engineering support |
Embedded team builds alongside your staff |
Platform-only, no delivery capability |
|
Core banking integration |
Pre-built connectors (SAP, Salesforce, ServiceNow) |
Custom development required per integration |
|
Governance tooling |
RBAC, PII masking, audit trail, guardrails |
Governance listed as a future roadmap item |
On deployment model: if your institution operates in a regulated jurisdiction with data residency requirements – the EU, Vietnam, Singapore’s MAS framework – on-premise or private cloud deployment is typically not a preference but a hard requirement. Cloud SaaS is appropriate for non-core workflows and bounded pilots where data sovereignty is not constrained.
On model-agnostic architecture: a platform that locks your institution into one LLM provider creates a pricing risk that compounds over time. We built AI Hive to run 11 or more models simultaneously – including OpenAI, Claude, Llama, Gemini, and Mistral – assigning the most cost-effective model per task type. Across our enterprise deployments, this approach reduces total LLM costs by 35-60% compared to single-vendor alternatives. We recommend reviewing our platform features and model-agnostic capabilities as part of any banking AI RFP process.
Why Banks Default to On-Premise AI Agent Deployment
Sovereign AI – the ability for organizations to deploy AI under their own laws, infrastructure, and data controls – has moved from niche concern to mainstream strategic priority across financial services. Deloitte’s 2026 enterprise AI report identifies it as one of the defining decisions for regulated industries entering production-scale deployment.
For banks specifically, on-premise deployment answers several requirements simultaneously:
- Data residency: customer financial data stays within the bank’s infrastructure post-deployment, with no data transiting a third-party cloud during inference or logging.
- Regulatory audit: on-premise systems give compliance teams direct access to decision logs, model inputs, and output trails – a requirement that cloud SaaS shared-responsibility models complicate significantly.
- Core banking integration: deep read-write integration with legacy core banking systems is substantially easier within the same network perimeter than across a cloud boundary.
- Air-gap capability: back-office environments that cannot connect to the public internet require Kubernetes cluster deployments that most cloud-native platforms do not support.
|
Factor |
On-Premise |
Cloud SaaS |
|
Data residency |
Guaranteed |
Vendor-dependent |
|
Regulatory certification |
Controlled internally |
Shared responsibility model |
|
Setup timeline |
2-4 weeks (with embedded engineers) |
Days to weeks |
|
Long-term cost control |
Predictable CapEx |
Usage-based, subject to pricing changes |
|
Best fit |
BFSI, healthcare, government |
Retail, SMB, fast pilot workloads |
Our approach to on-premise AI agent deployment for regulated banking environments uses Kubernetes clusters with zero data egress post-deployment. Your bank’s infrastructure receives the platform and agents fully configured, and nothing leaves after that point.
Banking AI Agent Deployments: 5 Things That Break in Production
The failure modes in banking AI agent deployments follow a consistent pattern. They are not AI model failures. They are integration, governance, and operational failures – all of which are predictable and preventable if you know where to look before committing to a platform.
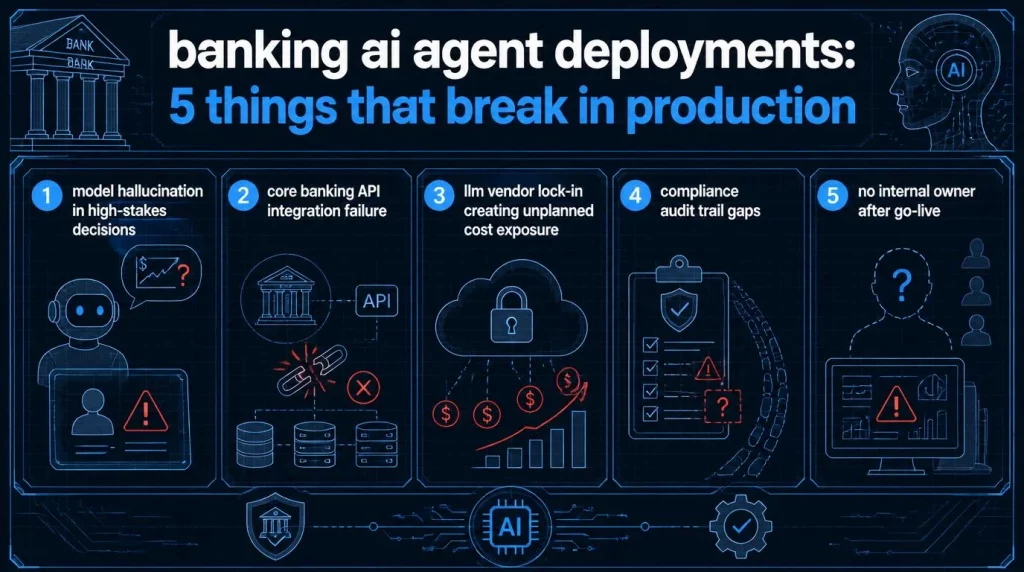
1. Model hallucination in high-stakes decisions
AI agents performing KYC eligibility determinations or credit scoring can produce confident-sounding but incorrect outputs when the underlying data is ambiguous. The fix is not a smarter model – it is output guardrails combined with mandatory human-in-the-loop review for any decision above a defined risk threshold. We configure this at the platform level before any banking agent goes live.
2. Core banking API integration failure
The most common production delay is an underestimated integration gap between the AI agent platform and the bank’s legacy core banking system. Many platforms offer “API integration” as a standard feature, but building a stable, authenticated, write-enabled connector to a 20-year-old core banking system often requires three to six months of custom development. AI Hive ships with 100+ pre-built connectors including SAP S/4HANA, Salesforce Financial Services Cloud, and ServiceNow. For systems outside that list, our embedded engineering team handles the integration build as part of the deployment scope.
3. LLM vendor lock-in creating unplanned cost exposure
Banks that built their first agents on a single LLM provider’s API discovered in 2024 and 2025 that pricing changes, context window limitations, and model deprecations created operational disruptions that they couldn’t absorb quickly. A model-agnostic architecture is the structural answer to this risk, but it requires building it in from the start rather than retrofitting it after the first cost crisis.
4. Compliance audit trail gaps
Regulatory examiners in the BFSI sector increasingly require decision-level explainability: what data the agent used, what rule triggered the output, who reviewed it, and when. Agents deployed without structured logging fail this requirement on the first examination. We build audit trail generation into every banking agent we deploy, aligning with GDPR Article 22 requirements for automated decision explainability and PCI-DSS audit standards. Our AI agent security standards for enterprise banking are documented in full – we recommend reviewing them before any vendor engagement.
5. No internal owner after go-live
Organizations with a named agent owner – a defined internal role accountable for agent performance and governance – show a 2.7x higher production-conversion rate than those without one, according to 2026 enterprise deployment data. The most common failure pattern is a successful launch followed by gradual agent degradation over six to nine months because no one owns model updates, integration maintenance, or performance monitoring. Our Ongoing Retainer option provides a minimum of 20 engineering hours per month to close exactly this gap for banks that do not yet have internal AI operations capability.
Compliance Requirements for AI Agents in Banking
Compliance for AI agents in banking operates across multiple overlapping regulatory frameworks simultaneously. Any platform you evaluate must address these requirements natively – not as a configuration option added after purchase. The table below maps the key regulations affecting most banking clients against the specific implementation requirements each one creates for your AI agent deployment.
|
Regulation |
Core Requirement |
AI Agent Implementation |
|
GDPR (EU) |
Data minimization, right to erasure, automated decision explainability (Art. 22) |
PII masking, data retention controls, audit trail with decision rationale |
|
PCI-DSS |
Cardholder data protection, access control, audit logs |
Encrypted storage (AES-256), RBAC, full activity logging |
|
SOC 2 Type II |
Security, availability, processing integrity |
Continuous monitoring, incident response protocols, availability SLAs |
|
HIPAA |
PHI protection for health-adjacent banking use cases |
Anonymization, role-based access, encrypted transmission (TLS 1.3) |
|
MAS TRM (Singapore) |
Technology risk management, data governance for financial entities |
On-premise option, risk classification, third-party vendor controls |
Beyond the specific frameworks, two principles apply across all jurisdictions. First, compliance requirements should be built into the agent architecture from the start – retrofitting governance after deployment consistently produces the audit trail gaps documented in Failure 04 above. Second, any platform that cannot provide a clear explanation of how it satisfies each framework’s requirements during the sales process is unlikely to satisfy a regulatory examiner after deployment.
We configure our pre-built compliance layers – covering PII masking, RBAC, AES-256 encryption at rest, and TLS 1.3 in transit – specifically against each client’s regulatory landscape as part of every banking engagement, not as a post-deployment add-on.
Why AI Hive Is a Top-Rated Partner for Banking AI Agent Deployment
Most enterprise AI platforms ask your bank to choose between two imperfect options: a heavyweight incumbent with a 12-month implementation roadmap and pricing that starts at $300,000 per year, or a lightweight tool that works in demos but cannot satisfy the compliance, integration, and governance requirements of a regulated financial institution.
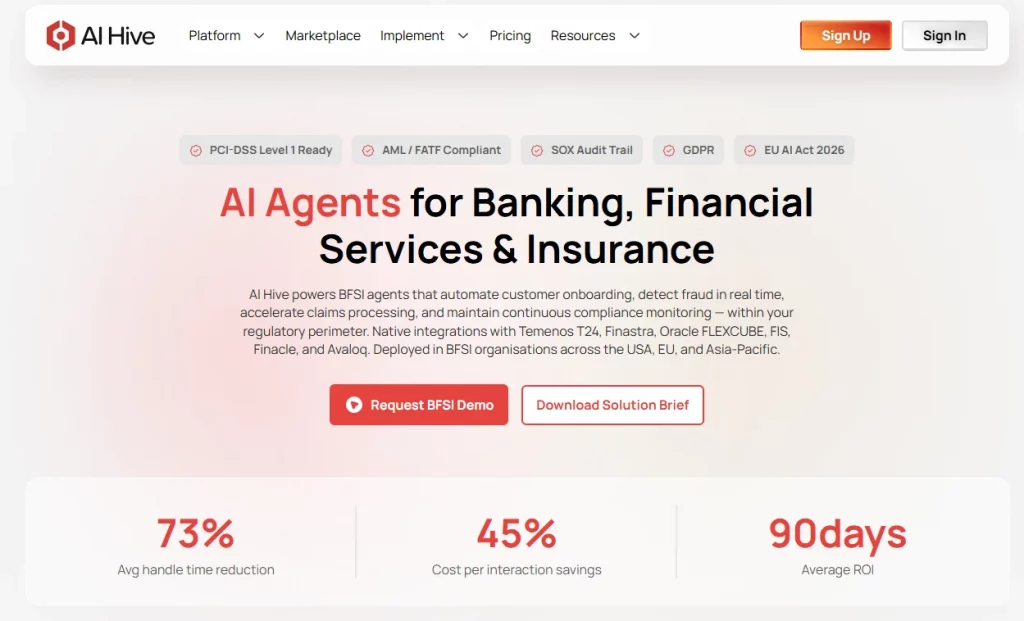
We built AI Hive to close this gap. Our platform combines production-grade technology with the delivery model that banks actually need to reach production – not just to run a proof of concept.
- On-premise and cloud hybrid deployment: we support Kubernetes-based on-premise clusters with zero data egress for institutions with strict data residency requirements, alongside cloud SaaS for workloads where sovereignty is not constrained.
- Model-agnostic architecture with BYOM: AI Hive runs 11+ LLMs simultaneously – OpenAI, Claude, Llama, Gemini, Mistral, and more – assigning the right model per task. Your institution avoids vendor lock-in and reduces total LLM cost by 35-60%.
- 500+ pre-built banking agent templates in our Marketplace: ready-to-deploy agents for KYC, AML screening, loan origination, fraud investigation, and compliance monitoring – deployed from template to production in under four weeks.
- AI Engineers for Hire: unlike Kore.ai or IBM Watson, which sell platforms and leave implementation to you or a third-party SI, AI Hive embeds senior engineers directly into your delivery cycle. We build alongside your team, inside your sprint cadence, at APAC cost efficiency.
- Compliance layers included from day one: PII masking, RBAC, AES-256 encryption, TLS 1.3, full audit trail generation, and output guardrails are not add-ons – they ship with every banking deployment.
- Transparent pricing starting at $1,500 per month: IDC reports that organizations achieve an average 2.3x return on agentic AI investment within 13 months. For a bank processing 10,000 KYC applications per month, the cost reduction from automating that single workflow typically exceeds our platform cost within the first 90 days.
AI Hive is a strategic product initiative of AHT Tech, a technology company with 18+ years of enterprise software delivery experience and 250+ engineers across the US, EU, Asia, and Australia. We are not an experimental startup selling platform access. We are a delivery partner that takes your AI agent from design to production and supports it after launch.
To explore how we approach banking deployments specifically – use cases, integration architecture, compliance mapping, and commercial terms – visit our BFSI solutions page.
Conclusion
Banking and insurance now lead all industries in AI agent production rates, with 47% of institutions running at least one agent in production as of Q1 2026 – projected to reach 63% by 2027. The gap between those deploying and those still piloting is not a capability gap; it is a platform, architecture, and governance gap. Institutions that resolve those three variables first will reach production in weeks; those that don’t will still be in pilot a year from now.
AI Hive is purpose-built to help banking institutions deploy AI agent for banking across KYC automation, fraud detection, compliance monitoring, and loan origination – with on-premise security, model-agnostic flexibility, and embedded engineers who own delivery alongside your team. If your institution is ready to move from pilot to production, schedule a 30-minute scoping call with our BFSI team – no NDA required to start the conversation.